

If your goal is to have a long-term real estate investment and you are ready to double or triple the speed at which you grow your rental portfolio, the BRRRR is the method for you.
Products and Tools Mentioned in this Post
Table of Contents
- How the BRRRR method works
- Before you buy: work the numbers backward
- Step 1: Buy
- Step 2: Rehab
- Step 3: Rent
- Step 4: Refinance
- Step 5: Repeat
- Example deal (illustrative numbers)
- Risks to plan for
- When BRRRR is the wrong choice
- Common mistakes
- Where to go next
- All our BRRRR articles
- Frequently asked questions
The BRRRR method stands for buy, rehab, rent, refinance, repeat. You buy a property that needs work, fix it to rental standard, place a tenant, refinance based on the new appraised value, and use the cash you pull out toward the next deal. When the numbers work, you end up owning a rental with far less of your own money tied up in it than a standard purchase would require.
This guide walks through each step in order. It covers how to size an offer before you buy, how lenders handle the refinance (seasoning, loan-to-value, and appraisal), and how to calculate the number that decides whether a BRRRR deal succeeded: the cash left in the deal. A full worked example shows the math, including what happens when the appraisal comes in low.
BRRRR fits investors who have some starting capital, can manage or hire out a renovation, are comfortable with short-term debt, and want to hold rentals for the long run. It is a poor fit for anyone who needs income right away, cannot absorb a delay of several months, or has no cushion if the rehab runs over budget.
Back to topHow the BRRRR method works
BRRRR is a buy-and-hold rental strategy with a forced-appreciation step in the middle. Instead of paying full price for a finished house and putting a down payment on it, you buy below what the house will be worth once fixed. The renovation creates equity, and the refinance lets you borrow against that equity.
The cycle has two financing phases:
- Short-term money pays for the purchase and rehab. This might be your own cash, a hard money loan, a private lender, or a home equity line of credit.
- Long-term money replaces it. Once the house is fixed and rented, a refinance loan based on the new appraised value pays off the short-term debt. If the new loan is large enough, some or all of your original cash comes back to you.
The whole strategy turns on one comparison: your total all-in cost versus the net proceeds of the refinance loan. If the refinance covers most of your costs, your capital is freed for the next deal. If it does not, you still own a rental, but your money is stuck in it, and the "repeat" step slows down or stops.
Cash left in the deal = all-in cost − (refinance loan amount − refinance closing costs)
All-in cost means the purchase price plus purchase closing costs, lender points and fees, the full rehab, and the holding costs (interest, taxes, insurance, utilities) until the refinance closes. Investors who track only the purchase price and rehab consistently overestimate how much cash they will get back.
Back to topBefore you buy: work the numbers backward
A BRRRR deal is decided at the offer. Once you have closed, the rehab and refinance can only protect the margin you bought, not create one. So the analysis starts from the end: what the house will appraise for, what it will rent for, and what a lender will lend against it.
Estimate the after-repair value conservatively
The after-repair value (ARV) is what the property should appraise for once renovated. Base it on recent sales of comparable homes nearby (similar size, bedroom and bathroom count, age, lot, and condition after repair). Use closed sales, not list prices, and favor the lower end of the range. An appraiser working for the refinance lender will not share your optimism, and a lower appraisal is the most common reason a BRRRR deal leaves more cash in than planned.
Estimate rent and operating costs
Check rents for similar renovated units in the same area. Then estimate monthly operating costs: property taxes, insurance, vacancy, repairs, capital expenditures (roof, HVAC, water heater replacements over time), and property management, even if you plan to self-manage. Put these into a rental property calculator to see net operating income and cash flow at a realistic loan payment.
Set a maximum offer
A common starting screen is the 70 percent rule: maximum offer = 70 percent of ARV minus rehab cost. The 70 percent rule calculator gives you that number quickly. Treat it as a filter, not a guarantee. The rule was built for flips, and it does not account for closing costs on both ends, lender points, or a refinance capped at 70 to 75 percent of value. As the example later shows, a deal bought exactly at the 70 percent mark can still leave cash in the deal once every cost is counted.
A better approach is to run the full deal through the BRRRR calculator before making an offer, then lower your price until the cash left in the deal and the post-refinance cash flow both meet your targets. For a deeper walkthrough of the inputs, see how to analyze a BRRRR deal before you buy.
Talk to the refinance lender first
Before you make an offer, find the lender who will do your refinance and ask:
- What is the seasoning requirement, and is it measured from the purchase date, the deed date, or something else?
- During seasoning, do you lend on appraised value or on the lower of cost and value?
- What is the maximum loan-to-value for a cash-out refinance on an investment property?
- Do you qualify the loan on my personal income and debt-to-income ratio, or on the property's rent (a DSCR loan)?
- Must the property be leased at closing, and what documentation do you need (lease, deposit receipts, rent ledger)?
- What are the typical closing costs, and is there a prepayment penalty?
The answers set your timeline and your maximum loan. Without them, the "refinance" in your plan is a guess.
Back to topStep 1: Buy
Find properties with a real discount
BRRRR depends on buying below the after-repair value by enough to cover the rehab, all costs, and the equity the lender will require you to leave in. Fully renovated listings rarely offer that gap. Look instead for properties where condition or the seller's situation keeps buyers away: dated homes needing cosmetic work, estate sales, vacant houses, tired rentals with long-term tenants, and owners who need a quick or as-is sale.
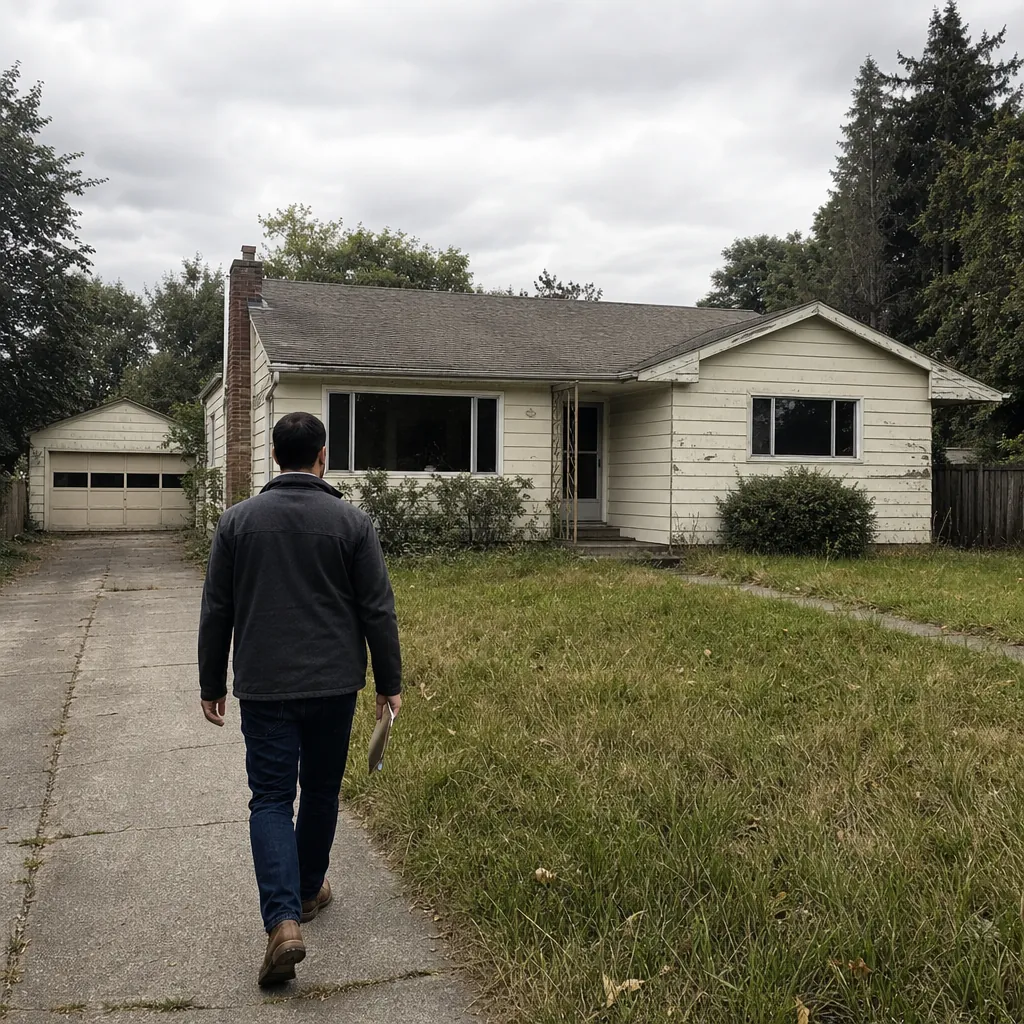
Off-market outreach, local wholesalers, agents who know investor-grade listings, and auctions are all common sources. For a structured approach, see screening criteria for finding BRRRR properties and the guide to finding motivated sellers.
Favor houses with good bones and cosmetic or mechanical problems over structural ones. Foundation, major water intrusion, and environmental issues are where rehab budgets break.
Choose how to fund the purchase and rehab
Many conventional lenders will not finance a house in poor condition, so most BRRRR purchases use one of these:
- Cash. Simplest and strongest at the negotiating table. It may also open the door to "delayed financing" on some conventional loans (covered under seasoning below).
- Hard money. Asset-based short-term loans, often covering a share of the purchase and most or all of the rehab through draws. Expect higher rates, points at closing, and terms of roughly 6 to 18 months, for example. The cost is worth it only if the deal still works after paying it. See BRRRR with hard money for how to model it.
- Private lenders. Individuals lending on negotiated terms. Put everything in writing, secure the loan with a recorded lien, and have a real estate attorney review the documents.
- HELOC on another property. Flexible and often cheaper than hard money, but it puts your other property at risk if the deal goes wrong. See using a HELOC to BRRRR.
Whatever you use, make sure the term is long enough to cover the rehab, the lease-up, the seasoning period, and a delayed refinance. Build in a few extra months.
Do the due diligence before closing
Get a professional inspection, and bring your contractor through the house before your contingencies expire. Check for open permits and code violations with the local building department, review the title report, confirm the zoning allows your intended use, and get insurance quotes for a vacant property under renovation. Insurance on vacant homes can be harder to find and more expensive than standard landlord coverage.
Back to topStep 2: Rehab
Renovate to rental grade, not showroom grade
The goal is a safe, durable, attractive rental that appraises well against comparable homes and attracts reliable tenants. Spend in this order:
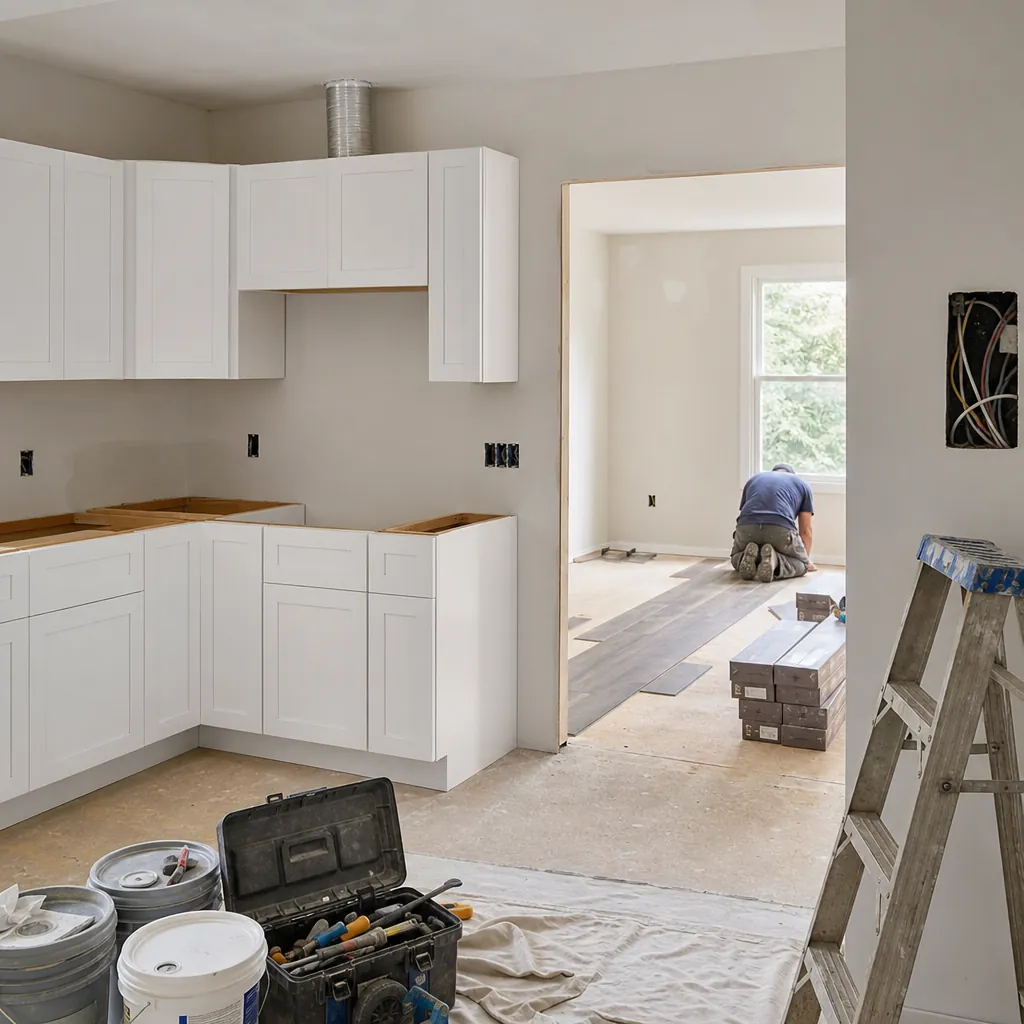
- Safety and systems: roof, electrical, plumbing, HVAC, water heater, smoke and carbon monoxide detectors, railings.
- Items that affect value and rent: kitchens, bathrooms, flooring, paint, lighting, adding a bedroom or bathroom where the layout allows.
- Durability: finishes that survive tenants, such as luxury vinyl plank over carpet, semi-gloss paint in wet areas, and mid-grade fixtures with easily sourced parts.
Match the finish level to the neighborhood's comparable rentals and sales. Over-improving rarely raises the appraisal enough to cover the cost.
Build the budget and protect it
Get a written scope of work with line items, and bid it to more than one contractor. Add a contingency, commonly 10 to 15 percent of the rehab for cosmetic jobs and more for older homes or bigger projects. Pay contractors in draws tied to completed work, not in large upfront amounts, and collect lien waivers as you pay. For more detail, see how to keep a BRRRR rehab budget under ARV targets.
Permits and timeline
Permit requirements vary by city and county. Electrical, plumbing, structural, and HVAC work commonly require permits and inspections. Unpermitted work can surface during the refinance appraisal, a future sale, or an insurance claim. Check with your local building department and confirm that your contractor holds the license your state requires.
Every month of rehab adds holding costs and pushes back the refinance. A realistic schedule with buffer time is part of the budget.
Back to topStep 3: Rent
Price and market the unit
Set rent from current comparable renovated listings and recently leased units, not from the highest asking rent you can find. Overpricing costs you vacant weeks, and lenders and DSCR calculations care about rent that is actually collected. Good photos, a clear listing, and fast responses to inquiries shorten vacancy.
Screen tenants consistently and legally
Write down your screening criteria (income relative to rent, rental history, credit, eviction history) and apply them the same way to every applicant. Federal fair housing law prohibits discrimination based on protected classes, and many states and cities add more protected classes and rules on criminal history, application fees, income sources, and security deposits. Have a local real estate attorney or experienced property manager review your criteria and your lease.
Document everything the lender will ask for
Refinance lenders often want a signed lease, proof of the security deposit, and sometimes proof of one or more rent payments. Keep clean records from day one. A BRRRR tracking spreadsheet makes it easier to keep costs, receipts, and rent records in one place for the lender and your tax preparer.
Back to topStep 4: Refinance
The refinance replaces your short-term financing with a long-term loan based on the property's new value. Three rules shape how much you get: seasoning, loan-to-value, and the appraisal.
Seasoning
Seasoning is how long you must own the property before a lender will refinance it based on its new appraised value rather than what you paid. Requirements vary widely by loan type and lender. Many lenders want several months of ownership, often around six months or longer for a cash-out refinance, and conventional guidelines change from time to time. Some DSCR and portfolio lenders will refinance sooner, but during that early window they may cap the loan at a percentage of your documented cost instead of the appraised value.
Some conventional loan programs allow "delayed financing" for properties bought with cash. You may take cash out soon after purchase, but the amount is generally limited to what you documented spending, and specific conditions apply. It helps you recover cash; it does not let you pull out equity above your cost early. Ask your lender whether it applies and what paperwork you need.
The practical point: your short-term loan and your cash reserves must last until the property is seasoned under your refinance lender's rules.
Loan-to-value
Loan-to-value (LTV) is the loan amount divided by the appraised value. Cash-out refinances on investment properties are commonly capped somewhere around 70 to 75 percent LTV, for example, with the exact limit depending on the lender, loan program, property type, credit score, and the property's rent coverage. The equity the lender requires you to leave in, usually 25 to 30 percent of value, is why buying deep below ARV matters so much.
The appraisal
The lender orders the appraisal; you do not choose the appraiser. Help the process by giving the appraiser a one-page list of improvements with costs, before-and-after photos, permit records, and the comparable sales you relied on. Make sure the house is finished and clean, with no open punch-list items. If the value comes in low, you can sometimes request a reconsideration with better comparable sales, but there is no guarantee it changes.
Choose the loan type
- Conventional cash-out refinance: often the lowest rates, qualified on your personal income and debt-to-income ratio, with stricter seasoning and limits on how many financed properties you can have.
- DSCR loan: qualified mainly on whether the property's rent covers its payment (the debt service coverage ratio). Rates and fees are usually higher than conventional, but personal income matters less and these loans can scale beyond conventional limits. Check your coverage with the DSCR calculator.
- Portfolio or local bank loan: held by the lender rather than sold, so terms can be flexible. These often carry shorter fixed periods or balloon terms, so read them closely.
For a side-by-side look at these options, see BRRRR refinance strategies: cash-out, DSCR, and portfolio loans.
Decide how much to pull out
Taking the maximum loan returns the most cash but gives you the highest payment and the thinnest cash flow. Taking less leaves more of your money in the deal but makes the rental safer. There is no universal right answer. Decide based on how much cushion the property needs to survive a vacancy or a major repair, and how soon you realistically need the capital for the next deal. Loan proceeds are generally not treated as taxable income, but the tax treatment of interest and the effect on your basis and depreciation depend on your situation. Ask a CPA.
Back to topStep 5: Repeat
The cash returned by the refinance funds the next down payment, rehab, or reserves. Before you roll it forward, set aside reserves for the property you just stabilized: several months of payments plus a repair fund is a common minimum. Many BRRRR portfolios get into trouble not because of a single bad deal but because the investor ran on zero reserves across several properties.
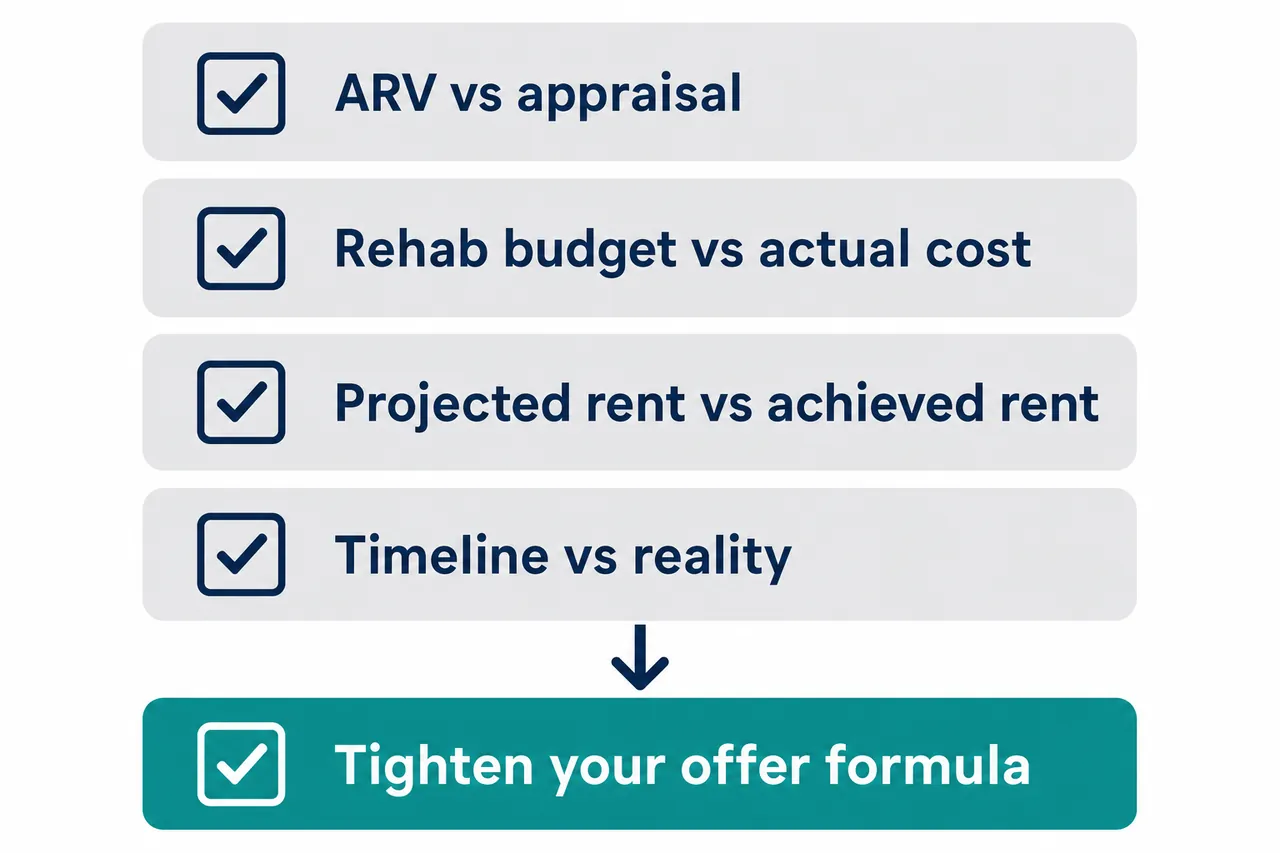
After each deal, compare your estimates with actual results: ARV versus appraisal, rehab budget versus actual cost, projected rent versus achieved rent, timeline versus reality. Tighten your offer formula wherever you missed. As the portfolio grows, lender limits, management systems, and contractor capacity become the constraints; see scaling BRRRR from 1 to 20 properties.
Back to topExample deal (illustrative numbers)
The numbers below are hypothetical, chosen to look realistic for a moderately priced US market in 2026. They are not a prediction of any market, rate, or result. The interest rate is an assumption for illustration only; get real quotes before analyzing your own deal.
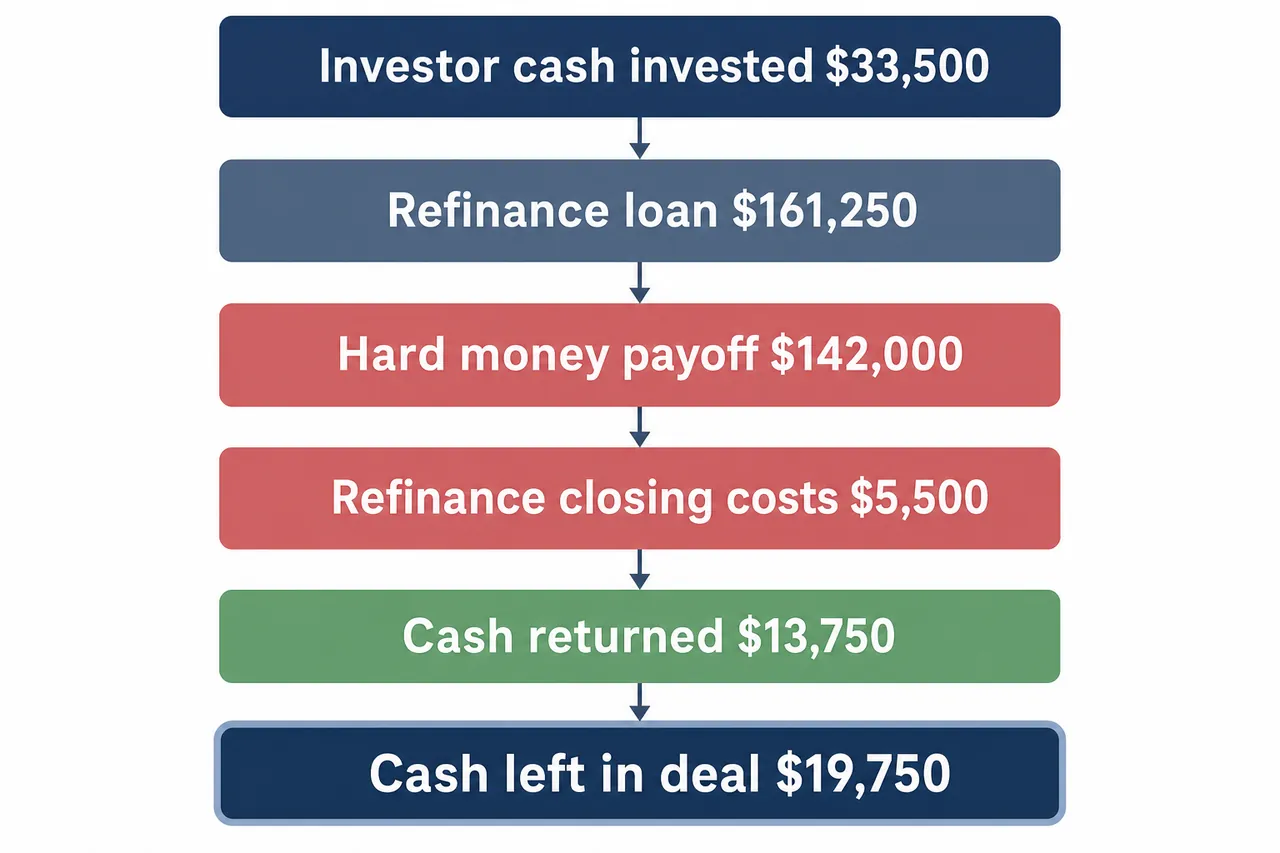
An investor finds a dated three-bedroom house. Comparable renovated homes support an ARV of $215,000, and similar renovated houses rent for about $1,950 per month. The contractor's bid is $36,000, and the investor adds a $4,000 contingency, which ends up being spent. A hard money lender funds 85 percent of the purchase price plus 100 percent of the rehab through draws. The project takes six months from purchase to refinance.
| Item | Amount |
|---|---|
| Purchase price | $120,000 |
| Purchase closing costs, lender points and fees | $6,500 |
| Rehab (bid plus contingency used) | $40,000 |
| Holding costs for 6 months (interest, taxes, insurance, utilities) | $9,000 |
| All-in cost | $175,500 |
| Hard money loan ($102,000 purchase + $40,000 rehab draws) | $142,000 |
| Investor's cash invested ($175,500 − $142,000) | $33,500 |
| Appraised value after rehab | $215,000 |
| Refinance loan at 75% LTV | $161,250 |
| Less hard money payoff | −$142,000 |
| Less refinance closing costs | −$5,500 |
| Cash returned to investor | $13,750 |
| Cash left in the deal ($33,500 − $13,750) | $19,750 |
| Equity after refinance ($215,000 − $161,250) | $53,750 |
Checking with the formula: $175,500 all-in − ($161,250 − $5,500) = $175,500 − $155,750 = $19,750 left in the deal. Same answer.
Cash flow after the refinance
Assume a 30-year fixed loan at 7.25 percent (illustration only). The principal and interest payment on $161,250 is about $1,100 per month.
- Rent: $1,950
- Property taxes: $210
- Insurance: $110
- Vacancy (5%): $98
- Repairs (6%): $117
- Capital expenditures (5%): $98
- Property management (8%): $156
- Total operating expenses: $789
- Net operating income: $1,950 − $789 = $1,161 per month ($13,932 per year)
- Cash flow after the loan payment: $1,161 − $1,100 = about $61 per month ($732 per year)
The cash-on-cash return is $732 ÷ $19,750 = about 3.7 percent, and the cap rate on the appraised value is $13,932 ÷ $215,000 = about 6.5 percent. You can rerun these with the cash-on-cash return calculator. For a DSCR lender, rent of $1,950 divided by the full payment including taxes and insurance ($1,100 + $210 + $110 = $1,420) gives a ratio of about 1.37, which would meet many lenders' minimums, though thresholds vary.
What the example teaches
The 70 percent rule was not enough. 70 percent of $215,000 is $150,500, minus $40,000 rehab, gives a maximum offer of $110,500. The investor paid $120,000. But even at $110,500, the all-in cost would have been about $166,000, leaving roughly $10,250 in the deal. To get all the cash back at 75 percent LTV, the all-in cost would need to be at or below $155,750, which means a purchase price near $100,000 with the same rehab and costs.
The LTV choice is a trade-off. If the investor took a 70 percent loan instead ($150,500), the payment would drop to about $1,027 and cash flow would rise to about $134 per month. But the refinance would return only $3,000 ($150,500 − $142,000 − $5,500), leaving $30,500 in the deal. Cash-on-cash would be about 5.3 percent ($1,608 ÷ $30,500), with less capital available for the next purchase.
A low appraisal changes everything. If the house appraised at $195,000, a 75 percent loan would be $146,250. After paying off $142,000 and $5,500 in closing costs, the investor would need to bring $1,250 to closing, and $34,750 would stay in the deal. The investor still owns a rental with equity, but the repeat step would stall.
Thin cash flow is the price of higher rates. The deal "works" as a capital-recycling move, but the monthly margin is small. One unexpected vacancy or HVAC replacement wipes out a year of cash flow. That is why reserves matter, and why some investors choose a lower LTV or a slower approach. See whether BRRRR still works at higher rates for more on this tension.
Back to topRisks to plan for
- Appraisal shortfall. The biggest single risk. Use conservative ARVs, and know in advance how much cash you could bring to closing if needed.
- Rehab overruns and delays. Hidden problems such as wiring, plumbing, rot, and pests show up once walls open. Every extra month adds interest and pushes back seasoning.
- Short-term loan maturity. If the refinance is delayed past the hard money term, extensions cost money and are not guaranteed. Confirm extension terms before closing.
- Rate and guideline changes. Rates and lender rules can change between your purchase and your refinance. A deal that cash flows at one rate may not at a higher one. Stress-test with a rate one to two points above your estimate.
- Lease-up and tenant risk. Slow leasing delays the refinance, and a bad tenant can damage the property and your cash flow. Local landlord-tenant law governs evictions, deposits, and notices, so learn your state's rules.
- Over-leverage across a portfolio. Several highly leveraged, thin-margin properties can turn a few bad months into a crisis.
When BRRRR is the wrong choice
BRRRR is one way to buy rentals, not the default. Consider something else when:
- You have no reserves. If a $15,000 surprise would sink you, the strategy is too fragile for your current position.
- Discounted deals do not exist in your market. If competition has pushed distressed properties close to retail value, forcing a BRRRR leads to leaving most of your cash in. Buying a solid rental with a standard down payment may be the better route; see the long-term rental investing guide.
- You need income now. BRRRR produces little or no income for months, and post-refinance cash flow can be thin.
- You cannot manage a renovation. Without a reliable contractor and time to oversee the work, the rehab becomes the weak link.
- You are just starting and plan to live in the property. An owner-occupied purchase with a low-down-payment loan may be easier. See BRRRR vs house hacking.
- The rent will not support a loan at today's rates. If the property only cash flows with most of your money left in, you are running a slow, expensive rental purchase.
Some investors use a slower version: buy with cash or low leverage, rehab, rent, and refinance later when values and seasoning support a better loan. The slow BRRRR framework explains how that works.
| Factor | BRRRR | Fix and flip | Buying a turnkey rental |
|---|---|---|---|
| Main goal | Own rentals while recycling capital | Profit from a sale | Own rentals with little work |
| Cash needed | Purchase and rehab cash, partly returned at refinance | Purchase and rehab cash, returned at sale | Down payment and closing costs, stays in the property |
| Timeline to income | Several months before stable rent | Lump sum at sale | Rent from the start |
| Main risk | Low appraisal, thin cash flow | Sale price and time on market | Overpaying, low returns |
| Workload | High at the start, then landlord duties | High, then done | Low at the start, then landlord duties |
| Taxes | Rental income and depreciation; varies | Gains on sale; varies | Rental income and depreciation; varies |
Tax treatment depends on your situation and holding period, so confirm with a CPA. If selling looks better than holding on a given property, the fix-and-flip guide covers that path, and some investors mix flips and BRRRR deals to restock capital.
Back to topCommon mistakes
- Counting only purchase price and rehab. Closing costs on both ends, points, and holding costs often add up to 10 percent of the project or more. Leave them out and your cash-left-in figure is wrong from the start.
- Using an optimistic ARV. Basing value on the single best comparable sale or on list prices sets up the appraisal shortfall.
- Not talking to the refinance lender before buying. Discovering a 12-month seasoning rule or a lower-of-cost-or-value cap after closing can wreck the timeline.
- A short-term loan that ends too soon. The term has to cover rehab, lease-up, seasoning, and delays.
- Over-improving. Premium finishes in a moderately priced neighborhood rarely raise the appraisal or rent enough to pay for themselves.
- Skipping permits. Unpermitted work can cause problems at appraisal, sale, or insurance claim time.
- Pulling out every dollar with no reserves. Maximum cash out plus zero reserves turns ordinary repairs into emergencies.
- Rushing tenant placement to hit a refinance date. A poor tenant costs far more than a few weeks of delay.
- Judging success by cash back alone. A deal that returns all your cash but loses money every month is not a win. Check both numbers.
For more on what goes wrong and why, see BRRRR mistakes that hurt returns.
Back to topWhere to go next
- Model your own deal, including cash left in and post-refinance cash flow, with the BRRRR calculator linked above, then compare loan options in the refinance strategies guide.
- If you are deciding between keeping or selling renovated properties, read BRRRR vs flip.
- If you are building your deal pipeline, start with the property screening criteria guide and the motivated sellers guide, both linked in the "Buy" section.
Run the numbers. See how much cash stays in the deal after the refinance, and the cash flow on the new loan. Free, no sign-up.
Back to top
Back to top
All our BRRRR articles
BRRRR articles on KDS Development, grouped so you can go deeper on any part of this guide. Newest first.
Guides and how-tos
- How to Execute the Slow BRRRR Strategy in 2026: Full Framework
- BRRRR Deal Calculator: How to Analyze Before You Buy
- How to Find BRRRR Properties: Screening Criteria That Work
- BRRRR Rehab Budget: How to Stay Under ARV Targets
- BRRRR Spreadsheet: Free Template to Track Every Deal
- Scaling BRRRR: How to Go From 1 to 20 Properties
- How to Find the Best Brrrr Property Deals for Your Real Estate Investment Strategy
- Financing Your Brrrr Home: Secure the initial loan and rehab costs
Explainers
- BRRRR Refinance Strategies: Cash-Out, DSCR, and Portfolio Loans
- BRRRR Mistakes That Kill Your Returns: Lessons From 50 Deals
- BRRRR With Hard Money: Making the Numbers Work
- SDIRA Real Estate Strategies: BRRRR, Syndication and More
- BRRRR in 2026: Does It Still Work at Higher Rates?
- Does the Brrrr Method Work: We Break Down the Pros and Cons
- Secure Your Financial Future: 10 Best BRRRR Markets for Real Estate Investment in 2023
- Brrrr Refinance: How To Make It Work
- Brrrr Multifamily: The Ultimate Guide to Maximizing ROI
- How to Analyze a Brrrr deal: Get Money Back
- Unlock the Secrets of FHA Loans: Can You BRRRR Your Way to Real Estate Riches?
- Brrrr With New Construction - Adding Fire to a Cold Investing Method
Comparisons
- Earning Infinite Returns on Real Estate: BRRRR vs Cash-on-Cash
- BRRRR vs House Hacking: Which to Do First
Calculators
Frequently asked questions
Can you get all your money back with the BRRRR method?
Sometimes, but only when the refinance loan minus its closing costs equals or exceeds your full all-in cost. With cash-out loans commonly capped around 70 to 75 percent of appraised value, that usually requires buying well below the after-repair value. Many solid deals leave some cash in, which can still be a good result if the cash flow and equity justify it.
How long does a BRRRR deal take from purchase to refinance?
It depends on the rehab size, how quickly you lease the unit, and your lender's seasoning rules. Six months to a year is a common range, and delays are normal. Plan your short-term financing and reserves for the longer end.
What is seasoning in a BRRRR refinance?
Seasoning is how long you must own the property before a lender will refinance based on its new appraised value. Rules vary by lender and loan type, and some lenders cap the loan at your documented cost until seasoning is met. Confirm the exact rule with your refinance lender before you buy.
Do I need to use hard money for BRRRR?
No. Cash, private lenders, HELOCs, and some renovation loans can all fund the purchase and rehab. Hard money is common because it lends on properties in poor condition, but its higher rates and points need to fit inside the deal's numbers.
Is BRRRR still worth doing at higher interest rates?
It can be, but margins are thinner. Higher rates raise the refinance payment, which reduces cash flow at a given loan amount. Many investors respond by buying at deeper discounts, refinancing at a lower LTV, or holding longer before refinancing. Run the numbers at several rates before committing.
Is cash from a refinance taxable?
Loan proceeds are generally not treated as taxable income because they are borrowed money. How the new loan affects interest deductions, depreciation, and a future sale depends on your situation, so review it with a CPA.
Back to top